
Nevada business tax notices: identify, document and respond
A Nevada business tax notice may concern a missing return, a payment posted differently than expected, an audit assessment or a later appeal decision. Those are different problems. Identify the agency, account, period and requested action before deciding whether to file, supply evidence, pay or challenge a determination.
This guide concerns Nevada Department of Taxation business accounts. Federal IRS letters and property-tax appeals have separate procedures.
On this page
Identify the issuing agency before choosing help
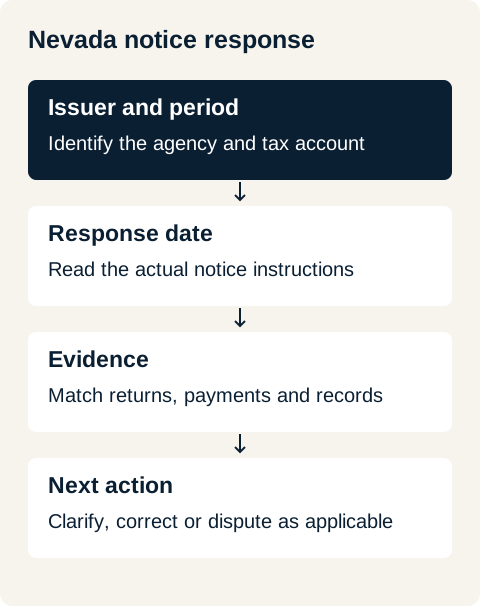
Read the full letter, including attachments and delivery instructions. Record the notice title, account, tax type, period, amount and response date. Keep the envelope or other delivery record where relevant.
For an IRS letter, use the federal notice guide. Do not use a Nevada business-tax appeal form to respond to federal correspondence. County property assessments and property-tax appeals also should not be treated as ordinary MBT, Commerce Tax or sales/use notices.
For a Nevada Department account, use the official contact and instructions associated with the notice. If uncertain about authenticity, find the Department through its official website before providing account or payment information.
Build a notice and account evidence file
Gather evidence for the exact taxpayer and period:
| Keep together | Why it matters |
|---|---|
| Complete notice and attachments | Establish the issue, instructions and stated deadline |
| Original and amended returns | Show what was reported for that period |
| Filing acknowledgements | Help distinguish a prepared return from a submitted one |
| Payment confirmations and account records | Help trace amounts to the correct account and period |
| Supporting books or payroll records | Explain the reported figures or proposed correction |
| Correspondence log | Record what was sent, when and to whom |
The Department's returns and payments guidance describes return copies, payment administration and digital notices. It explains that some digital notices can display a future date associated with planned mailing. If the timing is unclear, obtain an explanation rather than inventing a new deadline.
Distinguish a missing filing from a disputed assessment
If the notice says a return is missing, check the account and period against the return and acknowledgement you have. A payroll report for another agency, a draft return or payment evidence alone may not answer the missing-filing question.
If the figures on a filed return are wrong, identify the original and corrected amounts and the supporting records. Ask whether an amendment is appropriate and how it relates to the notice response. Submitting a correction does not establish that every other requested action is complete.
For a disputed audit assessment or deficiency determination, identify which amounts and grounds are contested. The Department's appeals FAQ describes informal explanation and the formal redetermination process. A conversation seeking clarification should not be assumed to suspend a filing or appeal deadline.
Protect the actual appeal route and deadline
The Department describes a petition for redetermination within 45 days from the date of a Deficiency Determination or Notice of Credit in the stated audit/assessment procedure. It separately describes a 30-day route for appealing an Administrative Law Judge's decision to the Nevada Tax Commission.
These are different stages and triggers, not a universal deadline for all Nevada letters. Read the actual notice and applicable procedure promptly. If timing, representation or rights are unclear, obtain qualified assistance before the stated date.
Keep proof of the response or petition, its contents and the submission method. Do not assume a request for more information, a payment discussion or a penalty-waiver request preserves every appeal right.
Choose help for the specific tax and stage
Tell a prospective adviser whether you need a missing return prepared, a payment traced, an assessment reviewed or representation in a formal proceeding. Ask who will perform the work, what authority or authorization is required and who is responsible for the next deadline.
The Nevada MBT, Commerce Tax and sales/use tax guides explain the underlying record and filing tasks. They do not replace the notice's response instructions.
Questions about Nevada business tax notices
Should I file the return again if the Department says it is missing?
First identify what was actually submitted, to which account and for which period. Ask the Department or responsible adviser how to resolve the discrepancy rather than creating an unexplained duplicate.
Does paying an amount automatically resolve an appeal question?
Do not assume that. Payment, correction and dispute procedures can have different requirements. Confirm what remains open and preserve the applicable response evidence.
Can my regular preparer handle every stage?
Confirm their actual scope and authority for this tax and proceeding. A routine preparation engagement does not automatically include representation. The Nevada business preparation guide and state hub organize the other filing resources.