
Nevada business tax preparation: separate the federal and state work
Nevada business tax preparation needs a work list that distinguishes the federal return from the state's business-tax accounts. Payroll, sales and use tax, and Commerce Tax review can involve different records and periods. An annual preparation fee should not be treated as confirmation that every connected filing has an owner.
Start by identifying the business, its actual tax classification, the period and the work already handled by a bookkeeper or payroll provider. Then identify what still needs professional review. This guide explains the Nevada-specific handoffs; it does not determine that every business owes every tax.
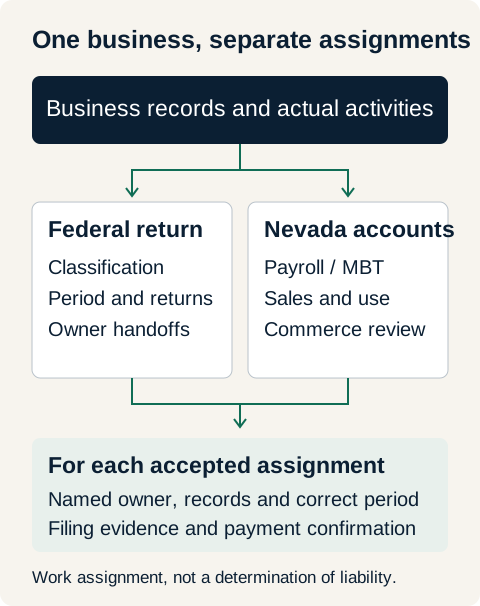
Work-assignment diagram by Financial Sales Insider. Federal return preparation and Nevada account work are separate assignments; the relevant obligations must be established for the actual business.
On this page
Start with the business's actual federal filing position
Give the preparer prior returns, ownership and election records, and details of changes. The name LLC alone does not settle the federal return arrangement. Use the national business tax preparation guide for the general classification, record and owner-handoff workflow.
Nevada's lack of individual state income tax does not answer the federal business-return question or remove separate Nevada business taxes. Identify the actual work rather than asking for a single Nevada company return as though it necessarily covers every account.
If an owner's household filing is also needed, name that assignment separately. Establish which business information must reach the person handling the owner's personal return preparation, and when it is expected.
Match Nevada accounts to their own records and periods
List the state accounts that exist, previous filings, periods under review and any outstanding correspondence. Ask who assesses whether an account or obligation applies, rather than assuming the current account list is complete or correct.
The goal is a usable handoff: the person receiving the records should know which taxpayer, account and period they concern. A bank export labelled taxes is not enough to distinguish a payroll-quarter adjustment from an annual revenue question.
Payroll and Modified Business Tax
The Nevada Department of Taxation describes Modified Business Tax as a payroll tax, with different employer categories and exceptions. For review, gather the relevant quarter's payroll reports and supporting employer-paid health-benefit information. Identify corrections and explain differences between payroll reports and the books.
Ask the payroll provider and preparer who handles the Nevada assignment. A provider preparing federal payroll forms has not necessarily accepted MBT work. Confirm who obtains the records, selects the applicable form and period, reviews any adjustment, submits the return and initiates payment where required.
Use the Department's instructions for the actual period and employer category. Do not apply a rate from an old return or another type of business merely because the form looks similar.
Sales and use tax records
For sales/use work, identify the account, reporting periods and locations or activities that need review. Provide the relevant sales reports, adjustments, exemption documentation where used and purchase records that may need examination for use tax.
The Department's sales and use tax page provides separate forms and period-sensitive instructions. Do not assume one rate, filing frequency or treatment covers every transaction. Have the responsible person explain what the return includes and which questions remain unresolved.
Separate preparing the sales figures from preparing and submitting the state return. If different people do those tasks, agree how they reconcile differences and how the business receives filing and payment confirmations.
Commerce Tax review
The Department's Commerce Tax guidance concerns Nevada gross revenue and industry classification. Give the reviewer the applicable reporting period, revenue records and information needed to assess the Nevada portion. Profit, nationwide sales and the initials in a business name are not interchangeable with that review.
Ask whether the engagement includes determining the filing position, preparing a required return and considering any related MBT credit under the applicable rules. Those are distinct questions; do not treat a possible credit as automatic or assume it has already been claimed.
Check the instructions for the actual period. A published due date for a prior year is not the next deadline for every business.
Compare what the preparation proposal actually includes
Nevada firms advertise different combinations of work. Rainbow Tax Service's business-preparation page discusses income and employment-tax services. Harger's services page lists preparation, payroll assistance and bookkeeping. Clayton Financial and Tax describes business and specialty returns as well as representation.
These are service-description examples reviewed on 13 November 2026, not recommendations or evidence that any named firm participates in FSI. The service list is a prompt to ask for a proposal identifying the work accepted for your business, not proof that everything appears in one fee.
A useful proposal identifies:
- The federal return and any separate owner information to be delivered.
- Each Nevada account and period included in the assignment.
- The record condition assumed and any separately priced cleanup.
- The person supplying records and the person resolving discrepancies.
- Who reviews, authorizes, submits and monitors each accepted filing.
- Who initiates payments and how completion is documented.
- What happens if a correction or notice requires more work.
A payroll provider can leave an assignment unallocated
Consider a hypothetical Nevada retailer whose payroll provider supplies quarterly reports while a different firm prepares the annual federal return. The presence of both providers does not establish who handles MBT or sales/use filings.
The owner should compare the actual agreements with the account list. If a state assignment is missing, resolve responsibility and the required records promptly. Do not assume the annual preparer will discover and complete it automatically. This example identifies a coordination gap; it does not conclude which taxes the retailer owes.
Resolve notices without losing the current filing task
If a Nevada notice is outstanding, list its account, period, requested action and actual response date separately from current preparation. Give the responsible person the full document and related filing/payment records. Agree whether they are explaining the account, preparing a correction or accepting representation at a particular stage.
Use the Nevada tax-help and notice routes to distinguish the state procedure from federal correspondence. An inquiry, amended filing or discussion with an agency should not be assumed to change a formal deadline. Keep evidence of what was submitted and track later correspondence.
Questions about Nevada business preparation
Does no Nevada personal income tax mean my business has no state filing work?
No. Evaluate the business's actual activities and state accounts. The Department administers business taxes separately from individual income-tax questions. Federal return preparation does not, by itself, establish that those assignments are covered.
Is MBT included when I pay a payroll company?
Check the agreement. Name the Nevada account, reporting period and tasks accepted. Ask who receives the records and who provides filing and payment evidence rather than assuming a general payroll label settles responsibility.
What proves the work is finished?
For each accepted assignment, keep the final filed copy, available submission/acceptance evidence, payment confirmation where applicable and any outstanding action list. A calculated amount, a draft return and a completed payment are different records. Ask who investigates a rejection or unmatched payment.