
Nevada Modified Business Tax filing: records, returns and payroll
Nevada Modified Business Tax filing is a separate employer-tax assignment. Completing federal payroll returns or paying unemployment contributions does not, by itself, show that the correct MBT return and payment have reached the Nevada Department of Taxation.
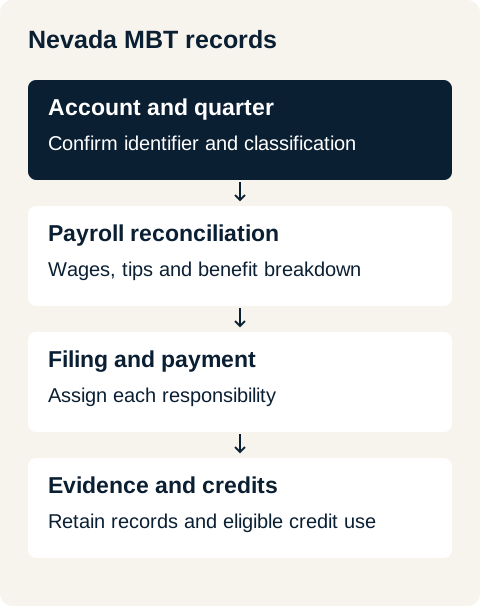
Before filing, identify the MBT account, employer category and calendar quarter. Then reconcile the wage and benefit records and agree who submits the return, authorizes payment and checks the result.
On this page
Identify the MBT account, quarter and employer category
The Department's MBT FAQs distinguish the MBT account from the federal employer identification number and the state unemployment account. Do not substitute one identifier for another when handing records to a preparer or payroll provider.
The applicable return depends on the employer's classification. General business, financial institution and mining work should not be treated as one universal calculation. Use the Department's MBT forms and current instructions for the quarter involved.
The Department describes quarterly returns and payment by the last day of the following month. An active account can require a return even when no wages or tax are due. Confirm the account's actual status rather than assuming that a quiet quarter closes the filing obligation.
Reconcile gross wages and employer-paid health benefits
Prepare a quarter-specific reconciliation before entering figures:
| Record | What to establish |
|---|---|
| Payroll register | The calendar-quarter wages and reported tips |
| ESD wage report | Whether the wages agree with the payroll records, and why any difference exists |
| Health-benefit records | The amount paid by the employer and its treatment under MBT instructions |
| Employee contributions | Amounts repaid by employees, distinguished from employer-paid benefits |
| Earlier filings | Corrections or carryforward items relevant to the quarter |
The MBT FAQ states that gross wages include reported tips and distinguishes qualified employer-paid health benefits from employee-repaid premiums. Do not use a general “insurance expense” ledger total without identifying what it contains.
For example, if the benefit invoice includes both employer and employee contributions, provide the breakdown. Ask the preparer to document the amount used rather than assuming the entire invoice is deductible.
Assign filing and payment separately
If a payroll provider handles MBT, confirm the exact account and quarter it files. If a different adviser calculates the figures or credits, specify how that information reaches the filer before submission.
Keep three distinct records:
- The final calculation and supporting reconciliation.
- A copy of the submitted return and its filing confirmation.
- Payment instructions and evidence that the payment reached the correct account and period.
The Department's returns and payments guidance explains that an electronic return copy is available after filing. A return copy and proof of payment answer different questions.
As of this guide's 13 November 2026 review, the Department's electronic-submission FAQ gives 7 December 2026 as the start of its new requirement, with specified waivers and exceptions. Check the applicable route and current instructions for your submission date; do not treat older paper instructions as the only route.
Resolve a mismatch or amended quarter with evidence
If payroll records and an MBT filing disagree, identify the original return, quarter, figures to change and supporting reason. Keep the original and corrected calculations together. Confirm the applicable amendment process with the Department or the responsible preparer.
Do not assume a claimed credit has already been approved or applied. The Department's guidance tells taxpayers to wait for its notification before applying a processed amendment credit to future returns.
If the issue is already the subject of a letter, use the Nevada business-notice guide to identify the notice and deadline. Correcting a return does not by itself establish that an appeal or response has been completed.
Check the Commerce Tax credit handoff
Where relevant, the Commerce Tax FAQ describes a credit toward MBT based on Commerce Tax paid and the eligible following quarters. Entity and affiliated-group rules matter.
Ask who verifies the payment, calculates the available credit and communicates its use to the MBT filer. The Nevada Commerce Tax guide covers that separate annual return and revenue review.
Questions about Nevada MBT filing
Is an unemployment filing also my MBT return?
No. The accounts, agency responsibilities and filings are distinct. Confirm the MBT submission rather than inferring it from payroll processing.
Can I ignore a quarter because no MBT payment is due?
Do not assume that. Check the active account and the Department's filing requirements, which include returns for periods without wages or tax due.
Does an annual business-return quote include MBT?
Only if that work is included in the engagement. Use the Nevada business preparation guide to assign the separate federal and state tasks, or return to Nevada tax help.