
Tax preparation in Orlando: choose personal, business or planning help
A household return, self-employment income and a property's business return can need different records and different preparation work. For tax preparation in Orlando, start with the return and tax year, then compare providers against the same assignment. If accommodation rentals are involved, identify the property and rent collector as well as the person preparing the income-tax return.
Ordinary individuals and families can use the personal-filing route below. Business owners can define the entity and owner returns separately, then use the planning section for decisions beyond annual filing.
Choose the work you need before comparing a service
| Your immediate job | Start here | Establish before agreeing a fee |
|---|---|---|
| A personal or family return | Individual preparation | Years, income sources, household changes and relevant states |
| A business return or owner information | Business preparation | Actual classification, records, returns and the owner handoff |
| A business decision or projection | Planning beyond the return | The decision, analysis and implementation responsibilities |
| An IRS letter | Federal notice triage | Notice code, period, requested action and actual date |
Individual tax preparation
Describe the year you need filed and whether the job involves an original return, an earlier unfiled year or a correction. Include wages, retirement distributions, investments, rental activity, self-employment and business-owner information where relevant. Tell the preparer about household changes, missing forms and any move or work in another state.
Florida does not impose a personal income tax, as the Department of Revenue explains in its new-resident tax information. That does not settle federal filing or a connection with another state. A recent arrival should give the preparer actual residence, work and income dates rather than requesting a Florida-only service from a postal address.
Ask which records the quote assumes you will supply: prior returns, income statements, relevant expense and credit records, payments and any correspondence. If rental activity is involved, explain whether the records concern personal reporting, an entity return or both. Flag incomplete booking or manager statements before treating the pack as ready.
Agree who answers preparation questions and what you receive at completion. Review the completed return before the applicable filing authorization; confirm who submits it and tells you whether it was accepted or rejected. Keep the return, available filing-status evidence and payment instructions. The personal preparation workflow develops those steps without assuming a particular provider offers every service.
Compare basic assistance with paid preparation
Heart of Florida United Way's tax-assistance page describes VITA basic income-tax preparation serving Orange, Osceola and Seminole counties. Use its current site information to check supported work, eligibility and seasonal arrangements. A regional program description is not confirmation of an appointment at a particular location.
The IRS's free-help guidance explains VITA/TCE and links to its locator. If considering software through IRS Free File, check whether it is currently open and supports the tax year and return you need. Provider conditions and state-filing charges can differ.
For paid help, identify the preparer, relevant return experience, secure document process and after-filing support. An office visit, drop-off arrangement and remote engagement can all be workable; confirm how questions and review will happen. Check the actual meeting location rather than assuming an Orlando-targeted web page establishes a city office.
Compare published Orlando preparation scopes
The following provider descriptions were captured on November 2, 2026. They illustrate different advertised scopes; current acceptance, professional status, office arrangements and fees need direct confirmation. They are not FSI listings or recommendations.
| Published service page | Scope relevant to your comparison | Question the proposal should answer |
|---|---|---|
| FloridaTaxPros | Separate individual and corporate paths alongside accounting and advisory work | Which personal and entity returns are included, and who coordinates them? |
| Thaney's Orlando page | Personal, corporate and estate preparation with broader business services | Which team and specialist work does this particular engagement cover? |
| NSKT's Orlando service page | Personal/entity preparation, planning and additional business-tax services | What is included in the proposed scope, and what location or remote arrangement is actually offered? |
| Upfront's preparation page | Individual and business preparation, records, review and later support | Who resolves incomplete records and handles questions before and after filing? |
Use the same household/entity/year outline for each quote. A package label or promise about refunds is less useful than a named return, responsible person and completion process. Published service descriptions do not establish that a firm has accepted your circumstances.
Business tax preparation
Give the professional the legal entities, owners, prior returns, relevant elections, reporting periods and places of activity. An LLC name alone does not establish its federal or Florida filing treatment. The Florida corporate-tax guidance explains different classification and owner circumstances; have the actual arrangement checked.
Ask whether the fee assumes reconciled books or includes cleanup. For operating and property businesses, keep the entities, payments and supporting records identifiable. If accommodation income is involved, a net deposit from a platform or manager may need reconciliation to gross activity and collection records. The property section below explains that additional task.
| Filing responsibility | What to have agreed |
|---|---|
| Records and cleanup | Who supplies the books, resolves missing statements and approves corrections |
| Entity preparation and review | Named returns, periods and jurisdictions, preparer and reviewer |
| Owner information | Who supplies each owner or personal preparer with the required business information and any later changes |
| Authorization and submission | Who approves and sends each return, then checks acceptance or rejection |
| Payments and completion | Who initiates payments, retains confirmations and supplies complete copies |
| Separate work | Whether payroll, sales/tourist taxes, local operating matters, amendments or notices are included |
An extension request and a tax payment need their own responsibilities and actual dates. Ask which returns the extension covers and how submission will be checked. Do not treat a filing appointment, signed draft or completed bookkeeping file as proof that every return and payment is finished.
The business preparation guide provides broader classification and completion questions. In an Orlando engagement, apply them to the actual entities and property locations. Recurring projections and decisions remain additional agreed work, as the planning section explains.
Planning beyond the return
Preparation reports the applicable period. The following questions concern a separate planning assignment: decisions, current projections and who implements the agreed work. Define that scope alongside the return responsibilities above.
Start with the decision the owner needs to make
Give a prospective adviser the current business financial statements, prior business and owner returns, ownership details and a short list of decisions awaiting approval. Identify what has changed: earnings, owner withdrawals, a new entity, a partner or a significant commitment.
Ask for a baseline projection before discussing alternatives. The baseline should make the assumptions visible and connect the expected business result with the owner's taxes and cash needs. A useful comparison explains which facts could change the recommendation, what work is required and who must approve it.
Owner compensation belongs in that discussion where relevant. An S corporation must pay reasonable compensation for shareholder-employee services before non-wage distributions to that shareholder-employee. The adviser should explain how duties, time and supporting pay evidence enter the review, and how any agreed change reaches payroll and the return. That rule is not a universal salary formula for every owner or entity. [1]
Compare planning depth across Orlando service offers
Orlando searches surface different kinds of planning content. HCPA's business-owner page is a menu of guides. BKHM describes business tax consulting, nexus studies, transaction planning and state or local work. Davis describes recurring planning alongside business, property and multistate services. Upfront's advisory page also names owner-compensation planning and implementation support. [2][3][4][5]
These are advertised scopes checked on October 30, 2026, not FSI partner recommendations or confirmed appointments. They show why a service label is only a starting point. Ask how the firm would apply its scope to your entities, financial records and upcoming decision. Do not assume planning is absent simply because a page also advertises return preparation.
For a profitable operating business without rental activity, compare the projection, owner-pay review, state analysis where needed and implementation process. For an owner with operating and property entities, also ask how records and responsibilities will remain distinct while the overall owner position is coordinated.
For rental activity, reconcile the income and tax ledgers
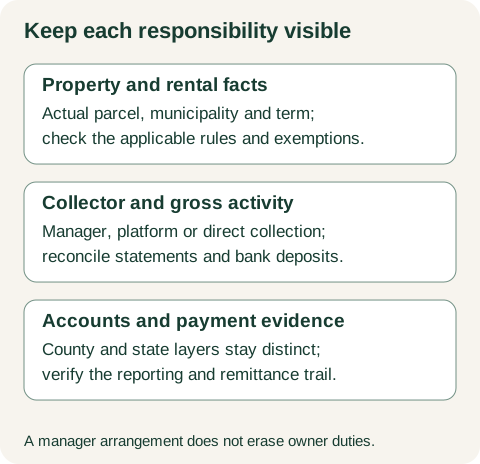
If the business includes accommodation rentals in Orange County, bring a schedule by property, booking channel and rent collector. Separate manager-collected receipts from direct rentals and identify where the tax records and payments are held. Do not infer what a platform or manager remits from a deposit description.
Orange County describes its tourist development tax as 6% on the covered consideration for accommodation rentals of six months or less, subject to the applicable rules and exemptions. This is the county tax, not a combined total including state sales tax and discretionary surtax. Florida DOR describes local transient-rental taxes as an additional layer. [6][7]
The county says a manager may use a consolidated tourist-tax account, but the owner should verify that arrangement and remains ultimately responsible for the required tax being paid. If the owner also collects rentals directly, the county identifies a separate individual account responsibility for those rentals. [6]
Ask the adviser to reconcile three things: gross rental activity in the records, income reported through the business and the applicable tax accounts. Bank deposits alone may not explain the gross receipts, deductions, collector or remittance trail. The review should identify missing statements and unresolved differences before relying on the numbers for an owner-tax projection.
Florida's commercial-rent repeal does not make this accommodation review unnecessary. The repeal applies to covered occupancy periods beginning October 1, 2025 and excludes transient accommodation of six months or less. It also excludes parking or storage for motor vehicles, docking or storage for boats, and aircraft tie-down or storage. Earlier covered commercial-rent periods remain taxable even if paid later. [8]
Confirm the property and business jurisdiction
Apply Orange County facts to property actually in Orange County. Establish the physical parcel and municipality rather than relying on an Orlando postal description or applying one property's treatment to every property in a group.
The Orange County Tax Collector's instructions identify Orlando among municipalities where the municipal Business Tax Receipt comes before the county receipt. They distinguish municipal properties from unincorporated Orange County and identify different arrangements for Bay Lake and Lake Buena Vista. Ask which physical locations and local processes are included when a business adds premises. [9]
These operating details support a complete engagement. They are not a substitute for evaluating entity and owner-income consequences. Florida's lack of personal income tax also does not remove every business return obligation; an LLC taxed as a corporation is one example requiring a separate classification review. [10][11]
What a useful first planning engagement should deliver
For an operating business, request a written baseline, the alternatives considered, the expected owner cash effect and an action list assigning responsibility. Identify the returns and people included. If an attorney, payroll provider or existing preparer has a role, record the handoff and approval needed.
For accommodation or property activity, add the property-and-collector schedule, reconciliation exceptions and responsibility for each tax account. Do not accept an income-tax strategy list as evidence that every local collection duty has been resolved.
Agree how results will be revisited when income or plans change. A useful review gives you a decision and a completion process, not only a list of possible deductions. Use the Florida filing overview for statewide forms and payment context.
Questions about an Orlando planning engagement
Does the commercial-rent repeal cover a short-term accommodation business?
Transient accommodations of six months or less are excluded from that repeal. Ask for a review of the actual property, rental term, exemptions and applicable tax layers rather than treating every rent payment alike. [6][7][8]
Does a property manager take care of all tourist tax?
Confirm the account and remittance arrangement. Orange County specifically tells owners to verify manager reporting and addresses owner-collected direct rentals separately. Ask for records connecting the bookings and collections to the relevant returns and payments. [6]
Can one adviser coordinate multiple operating and property entities?
Ask the proposed firm to identify the entities, owners and specialists in scope and show how their records connect without merging distinct duties. Check credentials separately from relevant experience. IRS guidance explains professional categories and representation rights; Florida DBPR identifies CPA-license verification routes. [12][13]
Further preparation questions
Does every Orlando business need the rental-tax review?
No. The property, collector and tourist-tax work applies where the actual accommodation activity requires it. An operating business without that activity still needs its own classification, filing and owner-information scope. Do not pay for an unrelated checklist in place of the returns or decision analysis you need.
Can a free-help program prepare any personal or business return?
No. Check the selected operator's current eligibility, supported tax year and return scope. A basic personal-return program does not establish acceptance of a separate entity return, complex rental records or every self-employment situation. If the work is outside scope, use the same facts to compare an appropriate private service.
Sources and review date
Planning comparisons were captured October 30, 2026; preparation comparisons and official filing/program material were checked November 2-3, 2026. The local tax propositions were rechecked against the applicable official guidance. Educational guidance; treatment depends on facts and tax year.
- IRS: S corporation compensation.
- HCPA: Business-owner guide menu.
- BKHM: Business tax service scope.
- Davis: Tax planning service scope.
- Upfront: Tax advisory scope.
- Orange County Comptroller: Tourist development tax FAQs.
- Florida DOR: Local-option transient-rental taxes.
- Florida DOR: Commercial-rent repeal.
- Orange County Tax Collector: New business receipts.
- Florida DOR: Personal income tax.
- Florida DOR: Corporate income tax.
- IRS: Preparer credentials.
- Florida DBPR: CPA verification, question 28.