
Tax preparation in Kingston: choose personal, business or planning help
For Kingston personal tax preparation, identify the year, household income and federal, New York and other-state returns. Wages or retirement income can be a standalone assignment. A financial report requested by another party does not establish that the personal return or an owner projection has been accepted.
For business preparation, name the actual entity, tax classification, owners, periods and records available. Distinguish company returns from financial reporting and a separate technical project. Ask which final figures or adjustments reach each preparer and who resolves differences. A report prepared for a lender or management should not be treated as an unexplained substitute for the records supporting the accepted returns.
Compare filing options for your actual return
Compare paid preparation, supported self-service software and basic assistance against the whole return and tax year. New York's income-tax filing resource center provides filing and assistance routes. The Taxpayer Assistance Program distinguishes guided sessions from software access and follow-up. Its 2026 guided assistance season has ended; check the current page for the relevant year, eligibility and arrangements rather than assume a local appointment is available. These individual filing options do not establish support for company returns.
The New York individual preparation section helps distinguish ordinary and more involved filing needs. For paid help, agree which person accepts the return and what records, review and questions the fee includes. A company or specialist project is not a condition of obtaining personal preparation.
Agree how each filing will be completed
Use an agreed secure document route, identify missing information and name who prepares and reviews each return. Confirm how you review the draft, authorize submission and receive each federal and state filing status. Ask who handles a rejection, what remains your responsibility and how final copies are retained. Submission, a refund and paying a balance are different matters. Amendments, notice responses and later planning need their own accepted scope.
For company and owner responsibilities, see New York business preparation. If an actual letter needs attention, the New York notice section starts with the issuer, taxpayer, period, requested action and response responsibility.
Business Tax Planning in Kingston, NY
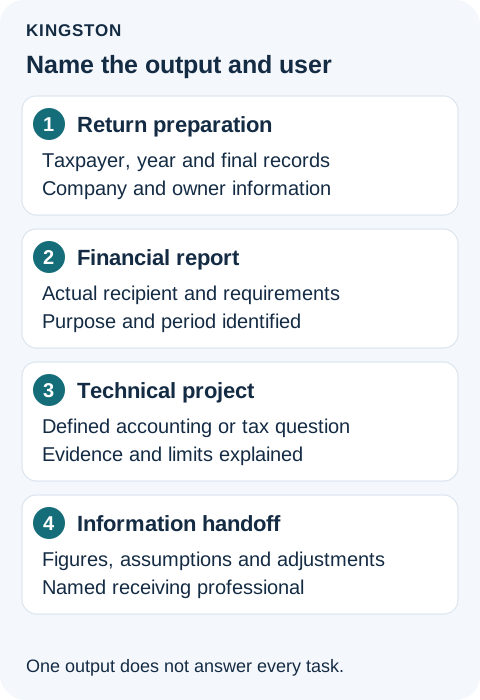
A company can need financial statements, a technical tax review and an owner's personal projection for different purposes. When choosing business tax help in Kingston, identify which output answers which question. A broad accounting package does not describe every analysis included.
State who needs the report and what decision it serves
Begin with the intended user and purpose. Is the request for internal management information, a report requested by a lender or investor, company tax analysis or the owner's personal position? Identify the period and decision date.
If another party requests a report, obtain its actual requirements and give them to the proposed professional. Ask which reporting service, records and review are needed. Do not assume that a tax return or an existing management report meets an unexplained request.
The useful first output is a scoped assignment: what will be produced, for whom, using which information and by when. The professional can then identify any separate tax questions. This guide does not select an assurance level or determine a reporting or tax treatment.
Compare the actual Kingston accounting and tax scopes
The inspected descriptions show different kinds of work. These are attributed observations, not rankings, verified FSI partners or confirmation of current capacity.
| Description inspected | Subjects described | What to clarify |
|---|---|---|
| Merck CPAs & Consultants services | Business tax compliance, accounting-method reviews, accounting for income taxes, financial statements and consulting | Which report or technical analysis answers your particular question? |
| Trast & Gyenes | Preparation, planning/advising, bookkeeping, payroll/QuickBooks and consultation | What specific output is included beyond the general service relationship? |
| UHY Kingston office | Federal tax and private-client gift, estate and trust expertise | Which actual company reporting and owner work is accepted in your proposal? |
Merck's substantial service page separately describes several technical and reporting subjects. For example, its accounting-for-income-taxes section lists tax provisions, current/deferred taxes and related reporting work. That is a description of services offered, not a conclusion that your business needs each item or that a particular accounting treatment applies. [1]
Trast & Gyenes presents a broader local tax/accounting relationship. UHY's office page is a capability and contact format, rather than a complete engagement description. Ask about relevant work without assuming that an unlisted service is unavailable or that every listed specialist is locally available. [2][3]
A Kingston postal label does not independently verify premises within Kingston city rather than the town or wider area. Confirm current scope and responsible people. Website technical examples are not authority for a tax strategy or reporting conclusion.
Separate company reporting from company and owner tax questions
Make the requested outputs recognizable before comparing fees:
| Output | Question to establish |
|---|---|
| Financial report | Who uses it, for what purpose and period, and under which requirements? |
| Company tax work | Which entity, return or proposed decision does the analysis cover? |
| Owner review | Which individuals and related company information enter the personal analysis? |
| Technical project, if needed | Which specific accounting or tax question requires additional review? |
These outputs can be connected without being interchangeable. A statement-preparation assignment does not, by its label, confirm an owner projection. Likewise, preparing a return does not describe the scope of every technical project.
Use the map to ask which figures, assumptions and conclusions pass between assignments. If a company report and owner analysis use different periods or information, ask how that difference is explained. No tax liability should be inferred from a statement total without the applicable review.
Ask what a technical review will produce
Merck's offer separately lists bookkeeping, accounting-method reviews and financial accounting for income taxes. Ask which actual question concerns your company and why a separate assignment may be needed. A menu is not a diagnosis. [1]
Prepare relevant policies and reports, returns, known prior adjustments, proposed transaction documents and recipient requirements, as applicable. Ask the professional which records are necessary and what remains unknown.
Request the question, period, evidence, assumptions, conclusion and limits in the work description. Establish who reviews the result and who implements any accepted action. A records update or changed software label does not itself demonstrate that the technical tax question was reviewed; ask what analysis occurred.
This approach defines a project without prescribing an accounting-method change, deferred-tax treatment or other technical outcome. Not every owner needs every service described on the researched pages.
Check the responsible reviewer and engagement boundaries
Ask about experience with the requested reporting and tax work, including any specialist contribution. New York's public-accountancy consumer guidance addresses credential checks, explanations of assumptions and reasonable alternatives, and written services, timing and fee terms. [4]
The IRS gives CPAs, enrolled agents and attorneys unlimited IRS representation rights. Those rights do not establish every reporting or planning specialty or include representation in the fee. Verify the individual and the actual assignment separately. [5]
Questions about Kingston business tax and reporting work
Does buying financial-statement preparation include my owner tax projection?
The service label does not establish that scope. Identify the report's purpose and period, then ask which company tax analysis and owner review are included separately and how their relevant assumptions are reconciled. Merck describes these as different service subjects. [1][4]
What should I ask if a lender or investor requests a report?
Obtain the actual recipient requirements and give them to the proposed professional. Ask which reporting service and supporting records are needed, what will be delivered and whether related tax analysis needs separate work. A generic tax return or website label does not settle those requirements. [1][4]
How is a specialist tax-accounting review different from routine bookkeeping?
Merck separately lists bookkeeping, accounting-method reviews and accounting for income taxes. Ask which technical question concerns your business and what analysis, evidence and written output are included. Do not assume that a records update settles it or that every company needs all those services. [1][4]
Records for comparing the proposed work
Keep a concise record of the business, owner situation, intended report user and tax question. Explain which work already exists.
Sources and review date
Sources checked October 30, 2026. Practice descriptions are attributed observations, not tax authority, independently verified credentials or current capacity.