
Tax preparation in Los Angeles for individuals and businesses
A personal return, a company return and a Los Angeles City business-tax renewal are different assignments. Start with the returns and years you need completed, then identify any separate notice, business-records or planning work. A firm may offer all of those services without including them in one fee.
| What you need | What to establish first |
|---|---|
| Personal or family preparation | The people, income sources, years and states involved, including information still expected from a business. |
| Business preparation | The entities, tax classifications, books and owner information needed for each return. |
| City business-tax work | The actual operating locations and activities, City account and filing period. Do not assume this is part of an income-tax engagement. |
| Help with a notice | The issuing agency, taxpayer, period, requested action and response date. A filing appointment does not establish responsibility for a notice. |
| Advice before a decision | The question still open, its timing and the records needed to compare alternatives. |
Personal tax preparation in Los Angeles
Tell the preparer whether you need an original return, a missing prior year or a review of something already filed. Describe employment, retirement, investments, rental activity, self-employment and information expected from partnerships or other businesses. Include moves and work in other states. The California individual preparation guide explains the broader filing choice.
For example, someone with wages and a separate freelance activity needs to establish how the business income and expense records will be reviewed alongside the personal documents. A folder of receipts is a starting point, not confirmation that the accounts are ready. Ask which missing items must be supplied and who resolves inconsistencies before the draft is prepared.
Agree who prepares and reviews the return, how you will exchange sensitive documents and what the price assumes about record quality. Before authorizing submission, review the completed draft and ask about unexplained figures. After filing, keep the final copy and acceptance information for each return; agree who follows up a rejection. Establish any payment instructions separately from the preparation fee. Uploading documents or paying the preparer does not confirm that a return was accepted or a tax payment made.
Basic assistance and California self-filing
The City's Free Tax Prep LA information directs residents to local volunteer preparation resources. Check the operator's current eligibility, supported returns, documents and season before arranging help. A program's published income figure does not establish that it accepts every return below that figure or has an appointment available.
The Franchise Tax Board's CalFile service is a separate California state-return route. At the November 3, 2026 check it lists 2023, 2024 and 2025 returns and requires a MyFTB account. Check the applicable eligibility and registration conditions. It does not complete a federal return or establish availability for a later tax year.
Business tax preparation in Los Angeles
Provide the legal entities, owners, tax classifications and prior returns, including election records where relevant. Agree which company returns, owner returns, years and jurisdictions are included. An LLC name alone does not tell the professional which filing work is required. The California business preparation guide covers that scope in more detail.
Name the person maintaining the books and any payroll or outside accounting contact. Identify whether the accounts are reconciled, what remains unresolved and who may approve corrections. If one firm prepares the company return and another prepares an owner's return, specify who sends the final owner information and who sends a revision. Keep the individual preparer informed about unresolved items without treating a provisional figure as final.
For each included return, identify the reviewer, required authorization, submitter and person checking acceptance or correcting a rejection. Agree how the business and owners receive copies and payment instructions. Make City registrations, renewals and activity reviews visible as separate work rather than assuming the federal or California quote covers them.
Compare service descriptions with the actual assignment
The provider examples below were checked November 3, 2026. They describe advertised services, not FSI listings, endorsements, verified credentials or current capacity.
| Published example | A useful question for your proposal |
|---|---|
| Mike Habib's Glendale and Pasadena service page presents individual, business and multistate work alongside planning and tax-problem services. | Which service area, returns and agency matters will this engagement cover? Regional service is different from an office in the City. |
| Weldon describes tax and accounting services and a process involving intake, secure documents and a plan. | Who reviews the upload, requests missing information and confirms the agreed work is complete? |
| TaxPlus describes preparation alongside bookkeeping, payroll and other business services. | Which of those services are included, and which require another engagement? |
A service menu cannot settle those questions. Use the same facts when comparing proposals and confirm the person responsible for your work directly. For an agency letter, the California notice-help guide separates the issuer and response task from normal preparation.
Planning beyond the return
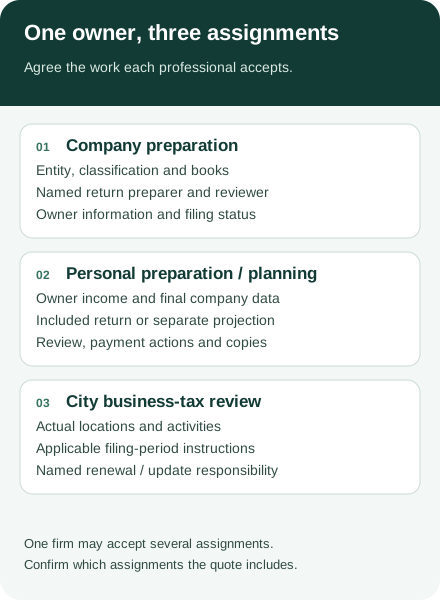
In the owner example below, company preparation, personal work and City review have separate records and completion responsibilities. One firm can accept several assignments; confirm each rather than treating them as a single automatic package.
Your business may need accurate annual returns, help with a decision still ahead, or both. When comparing a Los Angeles CPA or enrolled agent, separate the company's filing work, your personal tax position and any City business-tax assignment. A useful proposal explains who accepts each part and what you will receive.
Start with the business you actually operate
If activity is stable and the immediate task is filing completed periods, an annual preparation engagement may be enough. Confirm which business and personal returns are included, the records needed and how questions are resolved. A larger planning package is not automatically a better fit.
If profit, ownership or a transaction is changing, ask what forward-looking work is proposed before the decision is made. A return reports a completed period; a projection or transaction review uses current facts and assumptions to evaluate a question still open. Agree whether implementation and later reporting are included.
Give a prospective adviser a short ownership map. Identify each legal entity, its activity, its operating locations, the owners and the person responsible for its books. Include separately owned property and businesses in other cities. You do not need to send confidential returns before agreeing on a secure exchange method.
For a law-firm equity partner, the first question may be how the partnership's reporting will be coordinated with the partner's individual return. A commercial property owner may need an adviser who can work with the records for several properties and ownership entities. A profitable ecommerce owner should describe the brand, inventory arrangements and operating footprint rather than simply request a generic small-business package.
Ask the firm to describe comparable work it handles without revealing another client's private information. The useful answer identifies decisions, records and responsibilities. A list of industries on a website is not enough to establish that experience.
Los Angeles city business tax deserves its own review
Los Angeles Office of Finance renewal instructions distinguish taxable activities and their classifications. Most activities use gross receipts as the tax measure, while some use other measures. The instructions also address updating information after a sale or discontinued activity and explain that Business Tax Registration Certificates are not transferable. [1]
That creates a practical question for an established owner: does the engagement cover the City's business-tax records, or only federal and California income-tax returns? Keep those responsibilities separate in the proposal. A Los Angeles County address does not by itself establish the City of Los Angeles treatment for every operating location.
Where more than one activity is involved
Consider a hypothetical owner with a professional business and a separate product operation. Ask who will review the activity classifications, reconcile the relevant receipts and identify any available treatment under the applicable year's City instructions. Do not select a classification simply because another business uses it.
For that same owner, distinguish three assignments: the product company's return, the individual owner's estimates and the City activity review. One firm may accept all three, but a quote for company tax preparation does not establish that it does. Ask who reconciles the information across the assignments and who confirms any City update. Local registration work and advanced income-tax expertise are different matters to investigate.
When buying or selling an existing business
Add the ownership change to the planning brief before completion. Ask the adviser and transaction attorney which registrations, tax records and notifications need attention, who supplies the information and who confirms completion. Do not assume the seller's certificate becomes the buyer's certificate. The City's renewal instructions specifically address nontransferability. [1]
The official source cited here is the 2026 renewal guidance. Your adviser should use the instructions for the actual filing period. This guide does not calculate a City liability or determine an exemption.
Compare planning proposals by deliverable
When comparing a CPA for business owners in Los Angeles, ask for a scope that names the work and the person responsible. Business tax preparation and forward-looking planning should be distinguishable.
| Your situation | Ask the prospective firm |
|---|---|
| Several entities or partners | Which entity returns and owner returns are included, and who coordinates information between them? |
| Profit or owner income has changed | When will projections be updated, and what records are needed before that review? |
| A purchase or sale is approaching | What transaction support is included, and when do legal or valuation specialists join? |
| The business operates in several cities or states | Who determines the registrations, local reviews and returns requiring attention? |
| Bookkeeping and payroll are handled elsewhere | Who requests changes, records the decision and checks implementation? |
Ask what you will receive in writing: findings, assumptions, decisions, review dates and any work excluded from the price. A proposal that only says "tax strategy" leaves too much unresolved. Request clarification before comparing fees.
Check the professional and the meeting arrangement
Use the California Board of Accountancy's lookup to investigate a claimed California CPA credential and read the status information. The Board also provides guidance for out-of-state CPAs; absence from a California search is not by itself a final determination of authorization. [2]
For an enrolled agent, use the IRS status-verification process. Ask the individual who will lead the work to identify their credential and relevant business-tax experience. A credential check does not establish expertise in your industry. [3]
A firm advertising Los Angeles service may work remotely, operate an office elsewhere or offer local meetings. Ask which applies before choosing on proximity. Confirm the named contact, document exchange process and how decisions between meetings are handled.
Bring a decision brief to the first conversation
Describe your ownership, entity structure, operating locations and the filing task or decision you need help with. State any transaction date or current notice that affects timing.
Then ask the firm to propose the first stage of work. It might be a records review, a planning engagement or a scoped transaction review. Confirm what additional information is needed, what the fee covers and whether implementation and return preparation are included.
Can a remote tax adviser help a Los Angeles owner?
Potentially. Compare relevant California and local-business experience, credentials, communication and scope. A remote meeting does not remove the need to investigate the jurisdictions relevant to your operations.
Should I choose the proposal with the largest savings estimate?
Ask what facts and assumptions support it, what implementation costs are excluded and which conclusions still require review. An estimate for another owner does not establish your result.
Compare the accepted assignment before choosing
Keep a record of the company, owner and City work each professional agrees to handle. Compare fees only after those assignments, review dates and exclusions are clear. That leaves you with a defined relationship for the work you actually need.
For broader context, see the California tax-help guide.
Sources and review date
[1] City of Los Angeles Office of Finance. Business Tax Renewal Instructions. 2026 renewal guidance; use the actual filing-period instructions. No City liability or exemption determined here.
[2] California Board of Accountancy. License lookup. Read the status and out-of-state guidance; no individual professional verified by this guide.
[3] Internal Revenue Service. Verify the status of an enrolled agent.
Prepared for Financial Sales Insider. Refreshed 31 October 2026. General professional-selection information, not individualized tax advice. New preparation routes and three provider service descriptions checked November 3, 2026. CalFile lists 2023-2025 at this check. City renewal instructions rechecked for the retained 2026 activity and certificate statements; no later-period deadline, rate or exemption determined. Other credential background keeps its stated scope.