
Tax preparation in Lodi for individuals and businesses
Lodi personal tax preparation can cover wages, retirement, investment or freelance income for a stated year. Identify federal and California returns, other states and documents still missing. Completing an intake form or joining a waiting list does not confirm that the preparer accepted the returns or set a review date.
For business preparation, identify the actual tax classification, owners, reporting period and records available. Distinguish documents uploaded from records assessed as ready for preparation. Ask who reconciles incomplete accounts and supplies final owner information to the personal preparer, with any cleanup work separately accepted.
Confirm which office instructions apply to your engagement and which information remains outstanding. A provider's document cutoff is not automatically a statutory deadline or confirmation that every filing task is covered. Keep a specific planning question separate from the annual return organizer.
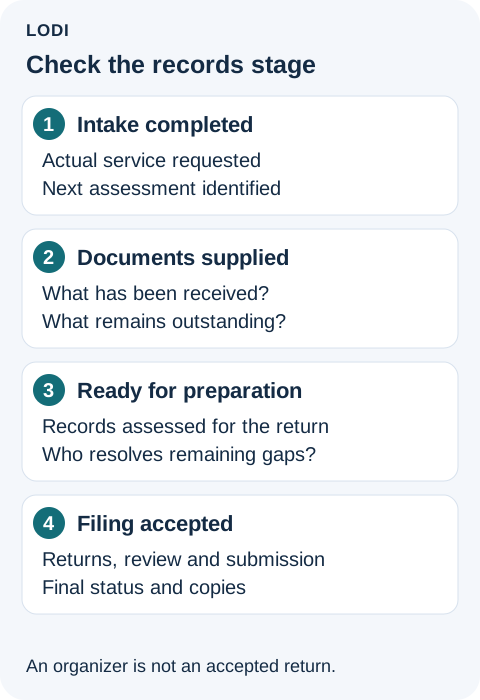
Choose the filing service that fits your return
Compare paid preparation with any official filing option that fits the entire return. CalFile is a California state-return service, with year-specific eligibility and form restrictions; it does not complete federal filing. Business or rental activity needs particular care when checking its qualifications. The California individual preparation guide explains the supported-year and eligibility limits, including the dated 2025 rules. Do not assume a new filing season is already supported.
For paid help in Lodi, compare how records, questions and draft review will be handled, whether remotely or through an agreed meeting. Use the California credential checks for the professional's actual category and authorization. An advertised service is not confirmation of experience with your return or current availability.
Know when the filing work is complete
Agree a secure document route and a list of missing information. Identify who prepares and reviews the return, how you check the draft and authorize submission, and how each federal and state filing status is reported. Ask who handles a rejection and what remains your responsibility. Keep final copies and payment instructions; submitting a return and paying a balance are separate steps. Later amendments, notices and new planning questions should have an explicit scope.
For company-specific filing responsibilities, use the California business preparation guide. If the immediate problem is an agency letter, the California notice-help guide separates the agency, period, deadline and response assignment.
Business tax help in Lodi: match intake and records to the assignment
A business-return questionnaire, a request for planning advice and a set of documents ready for review are different things. When comparing Lodi tax firms, establish which service you are requesting and what information the professional needs to do that work. Completing an organizer does not explain every decision your business faces.
The work needed determines the engagement. Ordinary personal or business preparation can be appropriate without an income minimum or an additional planning project. Keep company sales, profit, asset values and personal income distinct when describing the assignment.
Compare Lodi service offers and their intake boundaries
The following public descriptions illustrate different intake and service arrangements. They are research examples, not FSI partners, recommendations or independently verified credentials, results or capacity.
Sasaki Accountancy describes business accounting alongside preparation and planning for several taxpayer types. Its business page also describes contact during the year.[1] Ask whether you are requesting preparation, help with the underlying accounts or a particular forward review. A broad relationship can involve more than one assignment.
Lisa Sheeran's services page, checked October 30, 2026, stated that services had waiting lists. It provided separate questionnaires for business returns, individual returns, planning and bookkeeping.[2] Those are different service requests. The page does not confirm a current opening, a separate waiting time for each service or that a planning assignment has been accepted.
A1 Pro Tax Solutions describes preparation, planning, audit assistance and education for individuals and small businesses.[3] Explain the actual business and owner question so the candidate can distinguish it from routine filing or another service.
Green, Polack & Company describes a broader accounting and tax practice.[4] Its FAQs discuss providing documents, existing-client portal access and the effect of missing information on preparation turnaround.[5] Those details give you a useful second comparison: which records are ready for the specific work, rather than simply whether an inquiry form is complete.
Identify the records needed for the particular assignment
Tell the prospective firm what you want to understand or complete. Identify the company and owner work separately. If an annual business return is already assigned elsewhere but you need advice on an unresolved decision, explain that distinction before sending an organizer.
Ask the reviewer to separate three information states:
| State | What to clarify |
|---|---|
| Initial request completed | Which service was requested and what the next assessment involves. |
| Records supplied | Which documents were received and whether the professional has assessed their relevance or completeness. |
| Information ready for the agreed review | Which question the available records support and what uncertainty remains. |
A questionnaire may identify the service without supplying everything needed to examine it. Equally, uploading a large collection of records does not define the question. Ask for a targeted information request tied to the proposed preparation or planning assignment.
Does completing a tax organizer include business planning?
Confirm that separately. Identify the forward question, companies and owner positions to be considered, the records needed and the explanation you expect. Then ask whether that analysis is part of the proposal or requires another engagement. Do not treat the name of the intake document as the scope of the advice.
Read office document cutoffs alongside your actual assignment
Sheeran's FAQ page discusses office dates for receiving documents. Green's FAQs discuss when information is supplied and how missing material affects progress.[5][6] A firm's intake process matters, but it must be interpreted for the work you are actually requesting.
Distinguish the date the office asks to receive information, the time needed for the agreed assessment and any applicable obligations that the appropriate professional must confirm. Ask which of those dates a current instruction addresses. A general website calendar is not confirmation of your particular filing position or a completed planning review.
The captured FAQs also include legal, payment and refund statements, with older dated material on Sheeran's page. Those older statements and office calendar dates should not be used as current tax instructions. Confirm the applicable dates and responsibilities for your circumstances directly with the appointed professional.
If your records will arrive in stages, say so. Ask which work can be assessed with what is available and what depends on the remaining information. Avoid assuming that meeting one office cutoff means every related business and personal question will be resolved by the same date.
Resolve missing information before assuming the next step is covered
Green's discussion of incomplete information makes a practical question important: what exactly is missing, and who will obtain or explain it?[5] Ask whether the issue concerns a document not received, an unclear entry or additional work needed to make the records useful.
For example, a firm may need an explanation of figures already supplied rather than another copy of the same report. Ask the reviewer to identify the gap and the question it prevents them from answering. Clarify who will respond and whether preparing or correcting information is separately authorized work.
Keep that request proportionate. Sasaki's accounting and planning descriptions show related services, but their presence does not mean you must purchase every service together.[1] Establish what your existing team can provide and which additional assignment, if any, the candidate proposes.
If you are also changing advisers, use the business tax accountant handover guide for the wider transfer. This records-readiness discussion does not replace agreeing responsibility for unfinished work.
Verify the professional and describe your Lodi request
Use the California Board of Accountancy's lookup to check the correct CPA or firm identity, status and authorization.[7] For an EA, follow the IRS Office of Enrollment verification instructions.[9]
CPAs, enrolled agents and attorneys have unlimited representation rights before the IRS.[8] Those rights do not establish experience with your particular assignment. Ask who will perform and review the work.
Describe your business, annual personal pretax income, requested service and known information gaps. Agree a secure method before sharing sensitive records. An inquiry or waiting-list request does not confirm a provider, fee or review date.
Related information: California business tax planning resource.
Sources
- Sasaki Accountancy: business services.
- Lisa Sheeran: services and intake. Dated public waiting-list statement; confirm current terms directly.
- A1 Pro Tax Solutions: services.
- Green, Polack & Company: practice description.
- Green, Polack & Company: FAQs. Intake and records descriptions only; technical figures are not adopted.
- Lisa Sheeran: FAQs. Office-process comparison only; older calendar and technical statements are not current authority here.
- California Board of Accountancy: license search information.
- IRS: preparer credentials and qualifications.
- IRS: verify enrolled-agent status.
Sources checked October 30, 2026. General professional-selection information; confirm the actual assignment and current terms.