
Tax preparation in Fullerton for individuals and businesses
For Fullerton personal tax preparation, identify the year, income documents and federal, California and other-state returns needed. Explain whether the request is an original return, missing year or amendment, and identify records still outstanding. A household needing routine filing should not have to purchase notice representation or continuing planning.
For a business, state its actual tax classification, ownership, period and records. Ask who finishes bookkeeping cleanup and supplies final business information to the personal preparer. If an agency letter is also open, provide its issuer, taxpayer, period and requested action so the professional can distinguish it from the preparation assignment.
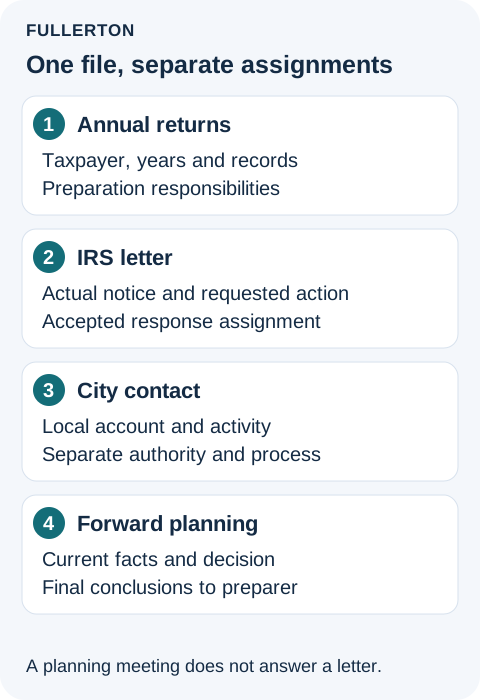
A City contact, an IRS notice and a current-year forecast can belong to different engagements. Confirm who accepts each matter and how any relevant final conclusion reaches the preparer. A scheduled planning meeting does not, by itself, assign an earlier letter or response date.
On this page
Choose the filing service that fits your return
Compare paid preparation with any official filing option that fits the entire return. CalFile is a California state-return service, with year-specific eligibility and form restrictions; it does not complete federal filing. Business or rental activity needs particular care when checking its qualifications. The California individual preparation guide explains the supported-year and eligibility limits, including the dated 2025 rules. Do not assume a new filing season is already supported.
For paid help in Fullerton, compare how records, questions and draft review will be handled, whether remotely or through an agreed meeting. Use the California credential checks for the professional's actual category and authorization. An advertised service is not confirmation of experience with your return or current availability.
Know when the filing work is complete
Agree a secure document route and a list of missing information. Identify who prepares and reviews the return, how you check the draft and authorize submission, and how each federal and state filing status is reported. Ask who handles a rejection and what remains your responsibility. Keep final copies and payment instructions; submitting a return and paying a balance are separate steps. Later amendments, notices and new planning questions should have an explicit scope.
For company-specific filing responsibilities, use the California business preparation guide. If the immediate problem is an agency letter, the California notice-help guide separates the agency, period, deadline and response assignment.
Business tax help in Fullerton: separate letters and planning
A proposal for ongoing planning is not an answer to every letter in the business file. A Fullerton owner may need current-year advice, help with a completed return, or a professional to handle a specific authority's inquiry. Identify the immediate matter before comparing firms that advertise all three.
The work needed determines the engagement. Ordinary personal or business preparation can be appropriate without an income minimum or an additional planning project. Keep company sales, profit, asset values and personal income distinct when describing the assignment.
Start with the authority, period and question
For a letter, identify who issued it, the person or entity addressed, the tax or account, relevant period and requested action. Preserve the complete document and attachments. Do not describe every contact as an audit or assume that a municipal account inquiry concerns the federal income-tax return.
The IRS explains that its notices can concern balances, changed refunds, questions about returns, identity verification or processing. It directs recipients to review the notice and act by the stated due date when a response is requested. If it changed a return, compare the notice with the return. [1] Those are IRS instructions, not a substitute for reading another authority's requirements. The broader California tax-notice guide explains how to distinguish the immediate agency and assignment.
When seeking professional help, explain the response date and action requested before discussing a long-term strategy package. Ask the professional whether they will review the actual document, handle the response and communicate with the authority, or only advise you on preparing it. If representation or legal advice is needed, confirm the appropriate professional scope and authorizations.
California owner tax-planning scope
Compare three assignments that can sound similar
Return preparation: preparing agreed returns from the relevant records. Ask which entities, periods and unresolved items are included.
A past-period matter: evaluating a notice, proposed adjustment, missing filing or potential error. Ask what documents will be reviewed, which authority and period are covered, who owns the response and what is excluded.
Forward planning: evaluating the current position and decisions still open. Ask for a useful output, implementation responsibilities and updates when facts change.
One firm may handle several assignments, but the engagement should identify them. A general promise to provide “tax support” does not explain whether a time-sensitive response or review of prior reporting is included.
Use a two-letter example to assess the handover
Consider a hypothetical owner with an operating business and rental property. The file contains a City business-registration contact about a property activity and an IRS notice about a return. The owner also wants a current-year forecast.
The useful first output is a matter list separating each authority, taxpayer, period, requested action and responsible professional. Then ask what evidence each review needs. A local registration record may help establish the activity, but it is not the underlying federal return or payment history. IRS guidance explains that supporting business records substantiate income, expenses, property basis and returns. [2]
For the IRS matter, the professional should explain the notice, records compared, response proposed and uncertainties within the agreed scope. For the forecast, they should identify which starting figures are reliable and whether the unresolved past issue affects them. This lets you see what is completed, what remains contingent and what must happen next.
You should not have to infer that buying an ongoing planning service also resolves the two letters. Ask for the tasks to be separately accepted and for the final outcome of each matter to reach the continuing adviser and preparer.
Understand the Fullerton local contact separately
Fullerton's registration guidance addresses business activity and maintaining a place or base of operations, and says separate registration may be required for branches or locations. The City also describes a compliance-discovery service contacting businesses and residential or commercial rental-property owners, with some applications outside the general online route. [3]
If that is the subject of your contact, confirm the actual account and current process through the City's published channels. Do not treat the contact as proof of an IRS or FTB liability, and do not assume an unrelated tax-planning engagement includes the City response. Name who supplies the property or activity facts and who confirms completion.
Move from resolving a matter to useful ongoing advice
After the immediate work is scoped, ask why the issue arose and what should change. Was relevant information missing, was a responsibility unassigned, or did the facts change after the last review? The answer should guide the next engagement rather than become a vague promise to prevent every future notice.
For current-year estimates, the IRS describes expected income and other tax inputs and the need to adjust for changed circumstances. [4] Ask the ongoing adviser how a concluded past-period matter changes those starting figures, if at all. Distinguish a corrected return, a revised projection and an implemented payment instruction.
For an owner with separately held property and an operating business, ask whether both arrangements and the personal position are within scope. A property issue should not disappear because the business's annual return was completed, and a business forecast should not be used as the entire personal plan.
Choose the professional for the actual work
Verify a claimed California CPA credential through the CBA lookup or enrolled-agent status through the IRS process. [5][6] Then ask about experience with the authority and matter in your file, not just general preparation. Confirm who will review the work, the firm's capacity for the response timetable and whether another specialist is needed.
Request written scope, fee basis, exclusions and responsibility for communications. Arrange secure document delivery before sharing notices, tax identifiers or returns. If authenticity is uncertain, use the relevant authority's official verification guidance rather than treating an unsolicited message as an instruction to send sensitive information.
verify tax-professional credentials
Questions before choosing Fullerton tax help
Does a new planning engagement replace responding to a notice?
No. For an IRS notice, review the actual instructions and response date. [1] Ask the professional to accept the specific matter and assign responsibility separately from current-year planning. Do not infer that a scheduled advisory meeting handles an earlier deadline.
Does every letter mean a return is wrong?
No. The IRS lists several reasons for notices, including identity checks and processing issues as well as return questions or balances. [1] Identify the actual document and requested action before reaching a conclusion. Other authorities' correspondence must be evaluated on its own terms.
What should a handover to a new adviser include?
The complete documents, relevant returns and records, work already performed, outstanding actions and who currently holds responsibility. Ask who will communicate the final conclusion to the preparer and ongoing adviser so that a closed matter does not remain an unexplained assumption in later work.
Sources
[1] Internal Revenue Service. Understanding your IRS notice or letter. IRS correspondence only; actual notice instructions govern.
[2] Internal Revenue Service. Recordkeeping.
[3] City of Fullerton. Business-registration guidance. Confirm the actual account, activity and current process.
[4] Internal Revenue Service. Estimated taxes.
[5] California Board of Accountancy. License lookup.
[6] Internal Revenue Service. Verify the status of an enrolled agent.